SPV Mechanics for Follow-On Investments in NYC Startups
Layered vehicles let existing investors double down when their fund can't match the full check.
Follow-on SPVs let investors back an NYC startup again when their fund cannot write the whole check. For a vehicle to work, it needs clear rights, sound economics, people who can run it well, and relationships that help it close on the round’s timetable. The entity is the easy part.
Why follow-on SPVs exist and the structural gap they fill
A fund can have a winning investment and too little dry powder to keep backing it. By Series A or B, its capital may be committed across the portfolio, while its remaining reserves must support other companies. A pro-rata right gives the investor the option to maintain its ownership percentage in a future financing. It does not supply the money to do so. An allocation is not a bank balance.
That gap makes a follow-on SPV a predictable tool. It pools separate capital for one investment, leaving the fund’s reserves intact. The same need arises when an allocation exceeds what the fund can absorb, concentration limits block further investment, or some LPs want more exposure to one company without backing the whole portfolio again. Solo GPs and emerging managers more often seek pro-rata rights that they can transfer so they can syndicate that allocation.
What a follow-on SPV actually is and who stands behind it
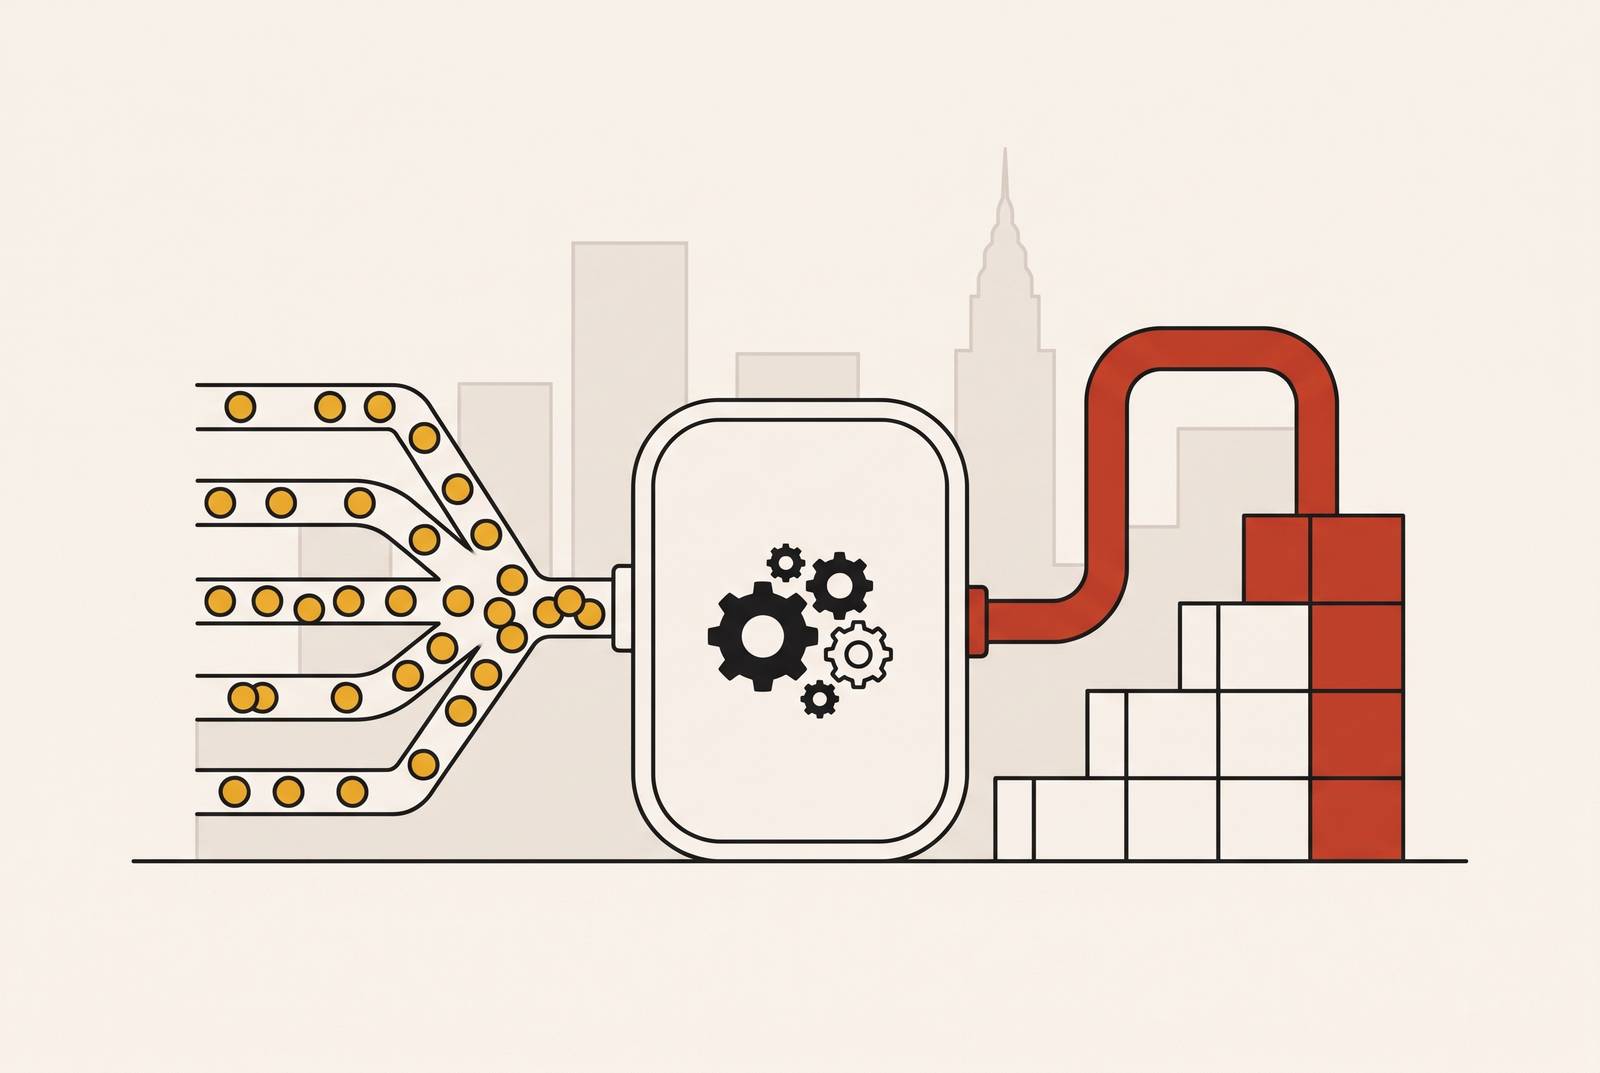
The solution separates the investment from the original fund. Allocations’ SPV guide explains how investors own proportional interests in a vehicle that owns shares in the startup. The company receives capital from one legal entity and issues the underlying security to it. The backers do not own startup shares directly. Their ownership sits one level removed.
Within that structure, the deal lead or sponsor sources the opportunity, secures the allocation, conducts diligence, recruits investors, and coordinates the transaction. The manager controls the vehicle under its governing documents and makes ongoing decisions. Depending on the structure, that role may be called manager, managing member, or general partner. Members or limited partners supply the capital. These roles distinguish who brings the deal together from who has authority after closing.
That distinction becomes important if the SPV later receives its own pro-rata rights. Those rights belong to the vehicle, and the manager decides whether to exercise or waive them. When exercised, the follow-on typically runs through a second, layered SPV. Yes, the vehicle can need another vehicle. The extra layer raises questions about governance and fees and gives no member a right of their own to invest again.
The lifecycle from trigger to closing and what happens at each step
The lead first secures or confirms the allocation, then gauges demand from existing LPs or new co-investors. Soft commitments come before formation costs. Once there is appetite, the lead forms the entity, nearly always a Delaware LLC, and drafts its operating agreement. That document defines economics, governance, and manager authority. Its terms will outlive the excitement of getting into the round.
Investor onboarding follows through subscription documents, accreditation verification, and KYC/AML checks. Most SPVs rely on Regulation D exemptions from SEC registration, so in most cases only accredited investors can take part. That reliance shapes how the offering can be conducted and how investors qualify. After onboarding, investors wire their commitments and the SPV aggregates the capital. It then funds the company and receives the underlying security, which may be preferred shares, a convertible note, or a SAFE.
Annual K-1s, investor reporting, follow-on decisions, and governance obligations continue for the life of the investment, often a decade or more. An acquisition, IPO, or secondary sale eventually brings proceeds into the vehicle, where fees and carry are calculated before distributions and dissolution. The deal itself may take weeks, but the entity stays active for years. The closing dinner is not a retirement party.
Legal formation and regulatory requirements a follow-on SPV must satisfy
Delaware LLCs are the standard choice because of their flexibility, established case law, and familiarity to institutional investors. The operating agreement governs manager powers, LP economics, carry calculations, and follow-on decisions. Transferable pro-rata adds another document to the picture. The lead cannot assume an existing right can move into an SPV without checking the Investor Rights Agreement, or IRA, where transfer typically requires founder consent.
Securities compliance is an obligation separate from forming an LLC. Regulation D’s Rule 506(b) and Rule 506(c) differ in their permissions for general solicitation and their investor verification requirements. The lead is responsible for accreditation verification before accepting capital, with identity and sanctions checks also completed before acceptance. Form D must be filed with the SEC within 15 calendar days after the first sale of securities. State-level blue sky filings may also be required, depending on investors’ domiciles.
Sydecar’s compliance guide covers how the Securities Act of 1933, the Investment Company Act of 1940, and the Investment Advisers Act of 1940 apply to SPV managers. These are not launch-day concerns alone. Their combined burden helps explain the appeal of purpose-built infrastructure, especially for recurring work. The most underestimated tail is often tax reporting, because the pass-through vehicle must issue K-1s to every investor each year, potentially for a decade or more.
How carry, fees, and platform costs affect what investors actually receive
Each layer of compliance has a cost attached. The costs of formation, onboarding checks, blue sky filings, and the platform cut into invested capital from the start. The vehicle needs tax preparation each year it stays active, and some SPVs also charge management fees during the holding period. Time gives modest annual charges room to accumulate. A clean entry price is not the same thing as a clean net return.
Carry creates a different question about incentives. The manager usually gets a percentage of profits above a hurdle, but LPs should check whether that percentage is based on gross or net proceeds. Gross-carry arrangements give the manager more at the investor’s expense. Meanwhile, the lead decides what to share with LPs, who may get updates only now and then. Where carry is calculated on gross proceeds, an incentive to distribute quickly can conflict with an LP’s interest in a more valuable secondary sale.
AngelList’s guidelines cap total SPV fees at a defined percentage of the amount raised, with fees prorated across LP commitments. For investors using several vehicles, repeated layers of charges can erode returns across the group of investments. Leads face their own economic test. A high entry valuation leaves less room for an exit multiple that brings in enough carry to make the legal and administrative costs worthwhile.
How platform infrastructure has changed the operational burden of running a follow-on SPV
That workload once meant coordinating a law firm, tax accountant, and bank, each with separate tasks and bills. Purpose-built platforms now bring formation, banking, onboarding, accreditation, KYC/AML, filings, capital accounting, tax preparation, and distributions into one stack. Fewer handoffs make the work easier to manage, though the duties stay the same.
Allocations positions itself as private capital infrastructure for SPVs, funds, and migration vehicles. Its Standard SPV has a flat setup fee of $9,950 covering formation, banking, investor onboarding, compliance, and tax preparation. Blue sky filings, KYC/AML, annual K-1s, and Form D filing are included. That model provides cost certainty before launch. It gives the lead a defined administrative price rather than a collection of separately billed services.
Sydecar provides a pre-launch framework, including an SPV Readiness Quiz, and guides covering legal compliance, management companies, PFIC considerations, secondaries, and term sheets. Its co-syndication guide explains how leads can bring their LP networks together and share economics within one SPV. Its layered-SPV guidance covers how to invest through other vehicles and the extra questions about governance and fees that come with them. These are examples of infrastructure supporting more involved structures. Platforms still cannot choose the right carry terms, investor minimums, governance provisions, or LP communication approach for the lead.
What follow-on SPVs mean for a founder’s cap table and investor relationships
For a founder, the visible result is consolidation. Twenty-five angel investors can invest through one legal entity, which keeps them from becoming twenty-five direct holders who each have their own information rights and documents to sign. Allocations’ pooling guide says that large venture firms look at the quality of the cap table during diligence. Continued participation can also show conviction from existing investors and strengthen the founder’s story to an incoming lead. One relationship is easier to manage than many.
But consolidation does not create more allocation in the round. When existing investors exercise pro-rata, they can leave too little room for a new lead whose strategic value goes beyond what earlier investors can offer. Institutional Series A and B leads sometimes push back on SPVs because they want fewer voice votes and simpler governance. That puts broad earlier commitments in tension with new demands. The cap table may be tidy while the negotiation is not.
For founders assessing those trade-offs, LP visibility deserves particular attention. The syndicate lead is the contact, while the investors behind the vehicle remain anonymous unless the lead shares the roster. That opacity can block access to useful hiring contacts, customer introductions, and follow-on advocates. A single line can conceal a valuable network. Founders should scrutinize the IRA’s transfer clause at seed, when closing quickly can overshadow the prospect of an investor later syndicating an allocation to people the founder never vetted.
Why the NYC funding environment in 2026 makes follow-on SPV fluency more urgent than before
Companies seeded in 2023, and some funded in 2024, are reaching Series A, while the earliest part of that cohort approaches Series B. Their early backers now face reserve and concentration decisions just as allocation competition intensifies. Series A and B rounds have grown a lot while seed deal volume has stayed steady. The distance between a seed fund’s planned reserve and the cost of its follow-on slot has widened.
That pressure has a local geography as well. Seed investors and portfolio companies cluster in Flatiron, SoHo, and nearby areas, where founders, co-investors, and potential round leads often share networks. Ramp’s lease at 28–40 West 23rd Street, Clay’s at 11 Madison Avenue, and Harvey AI’s at One Madison Avenue show how close together the companies that will need follow-on capital are. Proximity gives warm introductions a ready path. It does not settle whether a pro-rata right can transfer or who controls the resulting vehicle.
For founders and investors in this market, the lesson is about timing. Learning how the structure works before the round keeps founders and investors from having to learn its limits as they negotiate a competitive financing. The useful moment is before the first SAFE, well ahead of the Series B.
How in-person founder relationships in NYC are the actual foundation of follow-on SPV deal flow
A platform can organize a subscription, but it cannot manufacture the trust behind the wire. Co-investors commit because the lead has credibility built through prior interactions. Founders consenting to transferable pro-rata make a similar judgment about the investor’s ability to use it responsibly. Those decisions come before the paperwork can do its job. A tight closing schedule leaves little room to build that credibility from scratch.
NYC’s founder dinners, demo nights, and seasonal retreats bring people together again and again before anyone needs capital. Small, face-to-face gatherings let prospective co-investors know each other well enough for a warm introduction to have weight. The same relationships help counter the opacity of an SPV roster. Founders who know backers directly can reach the people behind the entity for hiring, customer introductions, and follow-on advocacy.
The practical implication is to invest in those relationships long before a term sheet arrives. Mechanical fluency makes the structure usable, while an established peer group makes it possible to move on a live allocation. Both take preparation before the deadline appears. An SPV can pool the money, but the people still have to say yes.